

On August 5, Google announced what appeared to be a corporate version of Nixon’s Saturday night massacre. Demis Hassabis stepped back from day to day operations at DeepMind. Jeff Dean, the founding father of Google engineering, is leaving to start a new lab called Discovery Loop, taking Sanjay Ghemawat, Quoc Le, and Oriol Vinyals with him. Koray Kavukcuoglu, DeepMind’s CTO, now has operational responsibility for DeepMind and Gemini
Dylan Patel and his colleagues at SemiAnalysis read this as a kind of failure in their recent newsletter “Gemini is Cooked but GCP is Cooking.” DeepMind has stopped being a frontier lab, they noted. The departures, they say, are a symptom of years of timid compute allocation and a bureaucratic, risk-averse culture. After all, Google had sophisticated conversational-AI systems well before ChatGPT, but was far more reluctant than OpenAI to put them in users’ hands. SemiAnalysis argues that Google’s failure to risk the core business has finally caught up with it.
It’s not a disaster for Google, though. In SemiAnalysis’s estimates, Google Cloud may be a much larger economic opportunity than pursuing its rivals in the frontier AI race. SemiAnalysis wrote “Our Tokenomics Model estimates that Gemini ARR was $12B in 2Q26. In contrast, by the end of 2027, GCP will be doing over $73B in third party AI ARR IaaS/TaaS and another $120B of TPU sales. $200B of external sales at high 30s EBIT margins vs a first party business generating just $12B today shows where the focus is.”
What’s more, after years of lagging Amazon and Microsoft in cloud revenue, Google seems to be gaining ground. Alphabet reported $24.8 billion of Cloud revenue in the latest quarter, up 82% year over year, compared with 37% growth at AWS and 43% growth in Microsoft’s Azure and other cloud services. The figures aren’t strictly comparable, though. Google Cloud includes Workspace and other applications, and Microsoft does not disclose Azure revenue separately from its cloud applications either, while AWS is pure cloud revenue. SemiAnalysis also estimates that TPU system sales added roughly $1.2 billion to Google Cloud revenue during the quarter.
Is this a choice by Google of profit over frontier ambition? SemiAnalysis compares it to past strategic missteps such as when IBM retreated from the PC into mainframe consulting, or when Intel retreated from Pat Gelsinger’s bold bets into its legacy chip business. Both ended up judged as major mistakes.
That may be correct. But there’s a second scenario that fits the facts, and is also rooted in history.
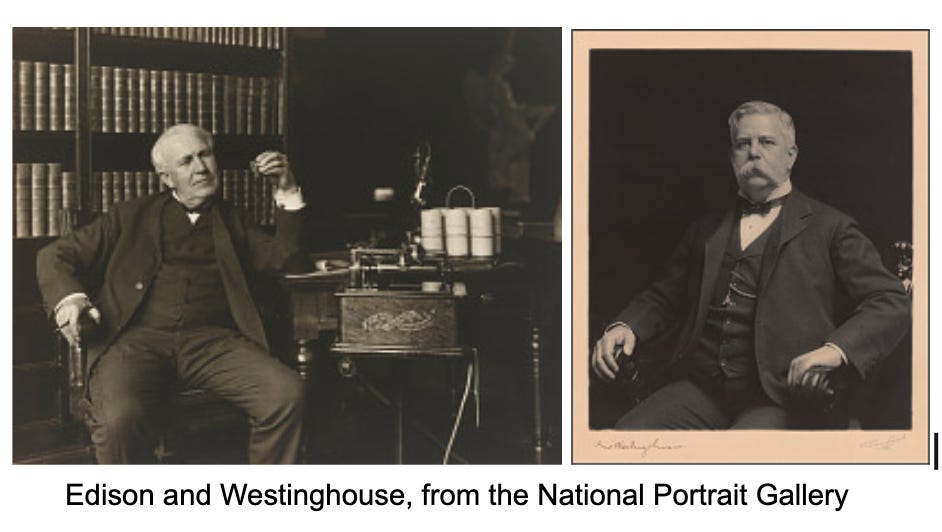
In the 1880s, Thomas Edison was famed as the hero of the electricity revolution. He had invented the first practical incandescent light bulb and commercialized it at scale, and had built the first commercial power plant in lower Manhattan. However, his system ran on relatively low-voltage direct current, which was practical over short distances but required generating stations close to customers. George Westinghouse bought Nikola Tesla’s patents for alternating current, which could travel for miles at high voltage and then be stepped down for ordinary use. Tesla had also developed electric motors and generators that ran on alternating current. By 1893 Westinghouse had lit the Chicago World’s Fair with AC. And by 1896, Westinghouse’s AC generators were sending power from Niagara Falls to Buffalo. Edison was the frontier leader, but Westinghouse won the race to diffuse electricity through society. (This is how it worked out even though Edison was, in many ways, right in the long term about the many applications for which direct current is superior. DC has returned as a crucial part of modern electronics, batteries, solar, EVs and high-voltage transmission. History rarely goes in straight lines.)
Jeff Ding’s book Technology and the Rise of Great Powers traces the relative impact of invention and diffusion during technology revolutions. Ding argues that nations that dominate the “leading sector” of a general purpose technology don’t reliably grow more powerful as a result. Diffusion is the defining factor. He posits that Britain’s edge in the first industrial revolution came less from inventing the steam engine and advances in steelmaking than from diffusing machinery through the whole economy so that many businesses, not just the steam engine manufacturers and the steelmakers, became more profitable. And America’s edge in the second industrial revolution had less to do with any single American breakthrough than with how fast interchangeable manufacturing, electrification, and eventually the automobile spread into every sector at once. Germany dominated many frontier industries, but there, growth and profits were concentrated in a few leading companies rather than diffused widely through society.
According to Ding, the importance of diffusion over frontier dominance continued in the 20th century. Though the US pioneered the electronics revolution, Japan appeared for a time to be winning the frontier race, at least in Ding’s narrative. It led the world in semiconductors, consumer electronics, and computer hardware through the 1980s, yet in the long run it still lost the information revolution to the US, a country that was worse at making the chips and better at putting computers to work throughout society.
I applied these insights to AI and its corporate adoption a few weeks ago in a review of Jeff’s book called Ordinary Engineers, Not Heroic Inventors. So reading SemiAnalysis, I wondered whether Google might be making the same strategic bet as Westinghouse. SemiAnalysis’s numbers can make the case that Google is betting on diffusion at least as well as the case that it is giving up on frontier leadership. So this could be read as a strategic argument inside Google that Google Cloud CEO Thomas Kurian won and that Demis Hassabis and Jeff Dean lost. Whether or not anyone inside Google describes it this way, the capital allocation increasingly looks like a strategy to become a platform for not just its own but for other people’s AI applications.
Kurian has been saying for a while that he wants Google TPUs to become “general purpose infrastructure,” serving Citadel Securities and the Department of Energy as readily as Gemini. Of course, the crucial question if we were using Ding’s framework isn’t whether Google sells lots of TPUs but whether those TPUs become complements to a broad wave of productivity-enhancing innovation in other parts of the economy.
Kurian has also defended selling compute to Anthropic as what happens when you’re a platform company. That sounds like someone who has argued that the bigger prize is being the layer that others’ AI runs on, competitors included, rather than doubling down on the potentially ruinous costs of the frontier AI race. After all, while SemiAnalysis didn’t go there, there’s a chance that if open-weight models continue to compress inference pricing, frontier labs may discover that model leadership resembles semiconductor fabrication, enormously important strategically but surprisingly poor as a standalone business.
Google also doesn’t need to win the frontier to dominate the edge. Its Flash-class Gemini models already run AI Mode in Search at enormous scale, with more user telemetry than almost any competitor. Google has enormous distribution advantages through Android, Chrome, Search, and Play. Perhaps they cede the expensive unprofitable frontier race and excel in the 120B space where affordability and local hardware are currently meeting in a sort of sweet spot. Returning to the history of electrification, it was ubiquitous small motors that powered the second industrial revolution, not giant dynamos. Buy one good small model team, my colleague Ilan Strauss speculates, and there may be no company better positioned to own the ordinary, everyday layer of AI the way Google already owns the ordinary, everyday layer of search. This may be a stretch. ChatGPT and Claude have made their own remarkable advances in the diffusion of AI, but IMO, their rhetoric about the way that AGI will concentrate enormous wealth and power in the hands of the winner doesn’t make a convincing case that they are operating with a diffusion strategy in mind. Meanwhile, both they and their customers are still in search of the widespread productivity uplift that diffusion of a general purpose technology brings.
In short, SemiAnalysis is probably right that Google gave something up on August 5, but possibly wrong about why. The evidence does not necessarily show that Google has abandoned technological ambition. Sergey Brin still seems to have plenty. But at least for the moment it may show a shift in where Google is allocating scarce AI compute and where it expects to capture economic value. It may be a mistake to assume that the AI race is about who builds the best intelligence. It may turn out to be about who builds the electrical grid. Maybe Google didn’t decide to stop trying to win so much as to decide that a different race was more worth winning.
1. As far as I’m aware, we don’t know the specs and efficiency of Google’s flash model serving search. It’s unclear then how close Google are or are not to the flash model frontier. They might already be the leader here. Or they might be subsidizing something inefficient.
2. What does OpenAI need to overcome?
In the last generation of competitive struggle, the following seemed to matter a lot: scale (for serving costs and network effects), hardware-software integration (use one to enter the other), cross-product data complementarities (search clicks or maps / phone data to monetize in ads), and product bundling (to envelope competitors).
Owning the user’s journey was key.
Can the current advantages enjoyed by frontier AI labs land up negating Google’s existing strengths in these areas above? I can imagine it weakening Google’s position vis-a-vie its end users, while reinforcing them for its producers. Why? Well Agentic AI consumes a ton of search, and a ton of maps, *but as an intermediary*. This is closer to producer (API) demand, perhaps. The consumer journey is being disintermediated. This must be a HUGE risk for Google. But for now manifests as higher API demand. And lower ads monetization. Just speculation.
3. Google’s ad network must be an enormous advantage. It is worth noting that OpenAI has had to start an ad network from scratch to avoid living inside Google’s ad network. How’s that working out for it?
The "winner takes all" mentality is almost being forced on the big AI companies given their CAPEX. It is not a given that either will "win" or be profitable. Open-source models are narrowing the performance gap, and their competitive advantage is foreseen by the US wanting to ban their use and importation. (Good luck with that.) There is already plenty of pushback on the siting of data centers for various reasons, and Google can read that public sentiment. Better to not be associated with those compute centers and sully what business they have.
It is also apparent that hyperscaling may not be necessary to achieve high performance, and certainly not appropriating the cultural artifacts for free to populate them for training. Just as electrification initially replaced the huge steam engines in factories with huge electric motors, it became obvious that the better way was to distribute electrical power to the point of use, and use small electric motors. Apple clearly wants to push appropriately-sized AI compute to edge devices, even as small as smartphones, which follows the electric power and motors history. If that is the future for AI, then Google can be the distributor of AI through apps and software running locally.